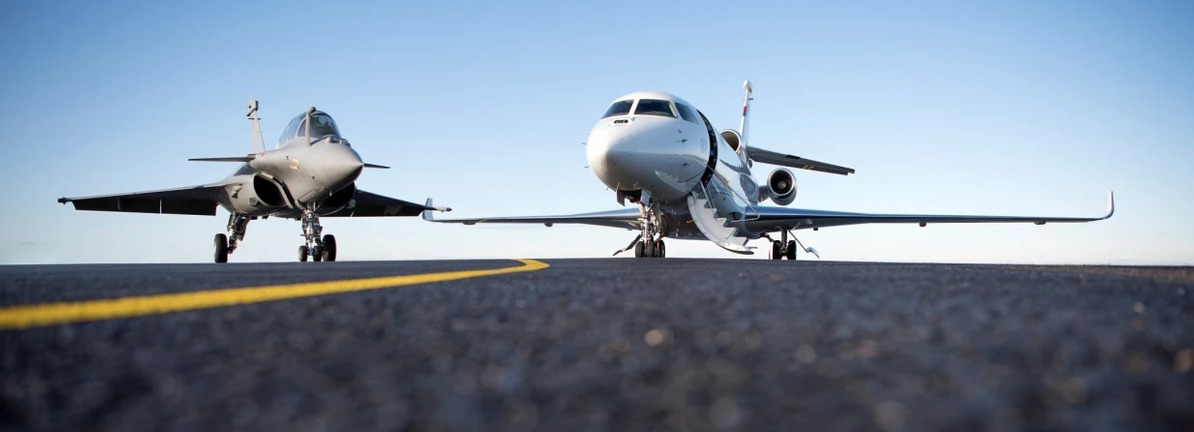
Dassault Aviation société anonyme has demonstrated notable stock performance, closing at €323.2, representing a 50.41% return over the past year. The company benefits from robust international demand, especially for its Rafale fighter jets, supported by major contracts with India and the UAE, along with ongoing negotiations with Indonesia. This demand provides long-term revenue visibility, positioning Dassault favorably amid rising global defense spending.
Analysts note that the company's current share price is slightly below the analyst target and significantly undervalued based on intrinsic value estimates. Despite this, some valuation metrics suggest the stock is only marginally cheaper than the broader European aerospace sector. Investors are advised to consider the risks, including potential supply chain issues and market sentiment shifts.
Valuation and Future Outlook
The narrative highlights Dassault's potential for growth, with fair value estimates around €325.06, indicating material upside if future margins and revenues materialize as projected. A detailed roadmap exists connecting current pricing to future profitability, though caution is warranted regarding supply chain disruptions and civil aircraft demand. The company’s backlog and international contracts are central to its growth story.
For investors seeking alternative or complementary opportunities, the article suggests exploring undervalued stocks, companies with solid fundamentals, and dividend-paying stocks, emphasizing the importance of diverse and informed investment strategies.
This analysis remains a general overview; individual investors should conduct their own due diligence. The article also promotes the use of tailored investment tools and trackers for managing portfolios effectively.

